We have been measuring and reporting our greenhouse gas (GHG) emissions since 2019 and have worked with Carbon Footprint Ltd to independently verify our assessments (ISO 14064-3:2019) since the 2020/21 reporting year.
As with all of our work at Epimorphics, we believe that better information leads to better decisions. That principle doesn’t just apply to the data platforms we build for our clients – it also applies to how we understand and reduce our own environmental impact.

Better data leads to better decisions
For us, carbon reporting isn’t simply about producing a number each year. It’s about understanding where our environmental impacts arise so that we can make better decisions and continually improve.
Like many organisations, we began with the data, methodologies and guidance available at the time, often aware that there are significant limitations in the available data and so the impacts reported – our approach has been to knowingly over estimate where there is uncertainty. Over the years we have continuously sought to improve our emissions estimates though using higher quality methods and data, based on GHG reporting standards. Improving the quality of greenhouse gas reporting matters because better evidence can lead to supporting better decisions. More representative estimates help us identify where our largest impacts really occur and so where to focus to help support emissions reductions in our value chain.
Our approach has therefore been one of continual improvement. Wherever practical, we have replaced generic assumptions with more specific, evidence-based estimates, while ensuring our methodology remains aligned with recognised greenhouse gas accounting standards.
This article describes two examples of that work during our 2024/25 reporting cycle:
- replacing spend-based estimates for our AWS cloud services with AWS customer-specific carbon footprint data; and
- developing a supplier-specific methodology for independent single-person consultancies, where no suitable product or organisational carbon footprint currently exists.
Our carbon footprint today
Since August 2024, Epimorphics has operated as a fully remote organisation and no longer maintains a permanent office.
As a result, our Scope 1 and Scope 2 emissions have reduced to zero, along with several Scope 3 categories associated with operating office premises, including fuel- and energy-related activities and operational waste.
Today, our reported emissions are entirely within Scope 3 and are principally made up of:
- Category 1 – Purchased goods and services (~74.1%)
- Category 6 – Business travel (~0.7%)
- Category 7 – Employee commuting and home working (~25.2%)
Over recent years we have progressively improved the quality of our reporting for Categories 6 and 7 through more detailed data collection and refined methodologies (see our Carbon Reduction Plan). During the 2024/25 reporting year our primary focus was improving Category 1, which now represents the overwhelming majority of our reported emissions.
Why spend-based estimates are only a starting point
Like most organisations, we have historically estimated the vast majority of our Scope 3 Category 1 emissions using the Greenhouse Gas Protocol’s spend-based (Environmentally Extended Input Output – EEIO) methodology.
Spend-based carbon accounting estimates emissions by applying an average carbon intensity (per £) for a purchase from a particular economic sector to the amount spent with a supplier. It provides a practical and internationally recognised approach where supplier-specific emissions data is unavailable and ensures that emissions across the economy are consistently allocated.
However, spend-based estimates inevitably have limitations because they measure expenditure rather than the actual emissions associated with a particular product or service.
For example:
- Purchasing the same laptop at different prices would produce different reported emissions, despite the physical product being identical
- A more sustainable/lower-carbon product that costs more could appear to have higher emissions than a cheaper alternative
- All computer hardware is represented using the same sector-average carbon intensity despite significant differences between products
- All consultancy services within a broad industry category receive the same emissions intensity, regardless of whether they are delivered by a global multinational or an independent consultant working primarily from home
These limitations are well recognised within greenhouse gas accounting (e.g. Climatiq introduction to spend-based emissions calculations). They mean spend-based estimates are valuable as a first-order approximation where no better information exists, but they should not be used to compare suppliers or make detailed procurement decisions.
The GHG accounting standards have a data-quality/method hierarchy supply chain footprinting, with most specific as the highest quality and rough proxy-based estimates as the lowest. EEIO data sits in the bottom of that hierarchy
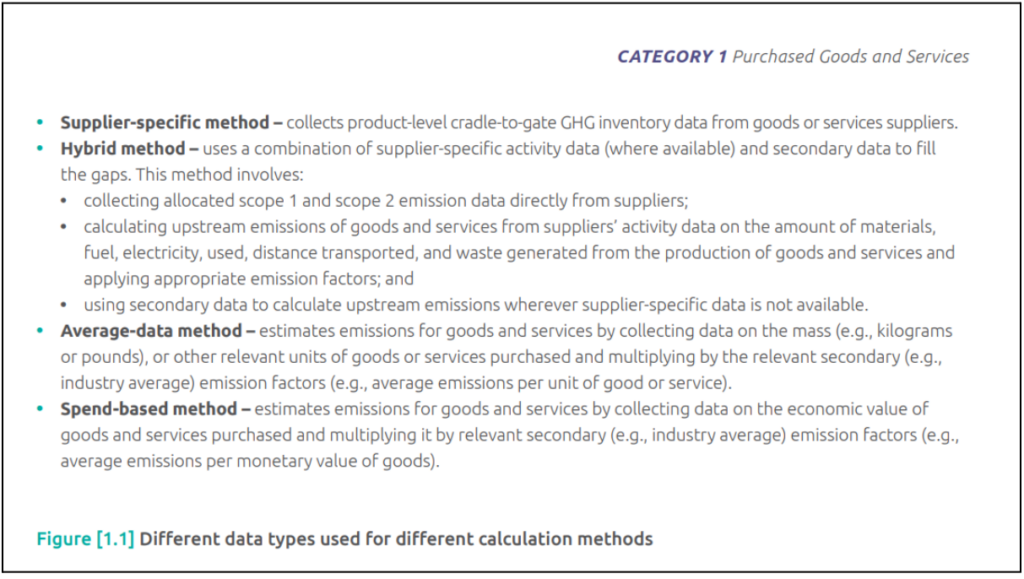
Our objective is to move up the methodology hierarchy.
Changes in spend-based multipliers by UK Gov published in 2026 & VAT calculation Correction
The spend based method outlined above depends on spend-based ‘multipliers’ (estimated kgCO2e/£) for categories of spend. In our case using Standard Industrial Classification (SIC) Codes to categorise spending. The standard multipliers we use are provided by UK Gov and are those used to estimate the overall UK carbon footprint. This year there have been significant changes in those multipliers after a switch in underlying data sources by the UK Gov / University of Leeds team that develop and maintain the multipliers. The changes are outlined in their 2026 methodology document. The goal of the changes are to improve the overall accuracy of the GHG footprints. The changes in data sources have been retrospectively applied to 2010 forward.
While overall the change in overall UK estimated emissions is small (a few % decrease) the impact in some specific industry sectors is much larger, e.g. forSIC code 63 (Information services) the change in source lead to a 45% reduction in the multiplier for the last common year between the sources (2022). These changes complicate the picture for this year.
It was also discovered, by the Epimorphics team, during our audit preparations, that the spend-based calculations were using outdated guidance regarding the inclusion of VAT, when it should have been excluding VAT. That means we were previously over-estimating our spend based GHG emissions by approx. 16.7%. The calculations have been updated.
Improvements during the 2024/25 reporting year
This year we focused on two areas where better information could materially improve the quality and usefulness of our carbon reporting.
AWS cloud services
Amazon Web Services (AWS) is one of our largest purchased services and underpins many of the data platforms and APIs we operate for our customers.
Historically we estimated the associated emissions using spend-based emissions factors. During 2024/25 we moved to using the estimated customer carbon footprint data provided through the AWS Sustainability Console.
This change follows significant improvements AWS has made to its methodology, including incorporating location-based electricity emissions and the majority of AWS’s own Scope 3 emissions. Following discussions with our independent carbon footprint verifiers, we are satisfied that this approach meets the requirements for our reporting.
For transparency and continuity, we continue to retain the equivalent spend-based estimate alongside the AWS figures so that historical comparisons remain possible and methodological differences are visible. It is worth noting that this year, because of the changes in spend-based multipliers (see above) the emissions estimated by the AWS customer footprint is for the first time higher than the spend-based method.
Further details of this change are described in our Carbon Reduction Plan.
Independent single-person consultancies
The second improvement addressed a challenge common across many knowledge-based organisations.
Epimorphics occasionally works with highly specialised independent consultants who provide expertise on specific projects. Under conventional spend-based reporting, these services would all receive the same generic consultancy emissions factor regardless of how the consultancy actually operates or how large the consultancy is.
We believed this could significantly overstate emissions for many independent consultants while providing relatively little insight into their actual environmental impact.
Rather than simply accepting the generic estimate, we developed a supplier-specific methodology in collaboration with our independent carbon footprint verifiers.
Developing a supplier-specific methodology
Our initial survey found that none of the independent consultants we work with had already produced organisational carbon footprints or customer-specific service footprints.
We therefore developed a simple questionnaire and supporting spreadsheet that enables consultants to collect the information needed to provide Epimorphics with standards-based estimates for the services they provide, without requiring specialist carbon accounting expertise.
The methodology separates emissions into two distinct elements.
Core operational emissions
These are emissions associated with operating the consultancy as a business, rather than with any individual customer or project. They include:
- home working;
- regular business travel and commuting;
- software licences and other operational services;
- office or co-working space, where applicable;
- business equipment and operational purchases.
The consultant’s annual operational emissions are estimated and then allocated to Epimorphics according to our share of their annual billable work (or, where billable hours are unavailable, our share of annual revenue).
Epimorphics project-specific emissions
These are emissions incurred solely because of work undertaken for Epimorphics. Examples include:
- project-specific travel;
- accommodation;
- venue hire;
- equipment purchased specifically for an Epimorphics project.
Because these emissions arise entirely from our work, they are allocated entirely to Epimorphics.
How the estimates are calculated
Home working emissions are estimated using the UK Government’s published home working conversion factors.
Operational purchases continue to use the UK Government’s Environmentally Extended Input Output (EEIO) spend based emissions factors where supplier-specific data is not available. Consultants are provided with a spreadsheet to categorise their expenditure and estimate these emissions using the published UK conversion factors.
This approach means that only the consultant’s own operational purchases continue to rely on spend-based estimates, while the overall footprint reflects how that individual consultancy actually operates.
For the consultants involved in our assessment, this was particularly appropriate because they:
- work primarily from home;
- make relatively limited operational purchases;
- have little or no non-domestic waste generation;
- have relatively low operational overheads compared with larger consultancy organisations.
The result is a considerably more representative estimate than applying a single generic consultancy emissions factor to all professional services expenditure.
Continuous improvement
There is no single perfect methodology for estimating Scope 3 supply chain emissions.
Reporting standards continue to evolve, suppliers are beginning to provide more product- and service-specific emissions data, and new guidance is helping organisations move beyond broad industry averages.
Our objective is not to produce artificially low emissions figures. It is to produce figures that better reflect reality, are transparent in how they have been derived, and provide a stronger basis for future decision-making.
We expect this process of continual refinement to continue. As higher-quality supplier data becomes available, we will continue replacing generic assumptions with more representative evidence wherever practical, helping us improve both the quality of our reporting and our understanding of where meaningful emissions reductions can be achieved.
Further details are described in our Carbon Reduction Plan.